ChinaCN
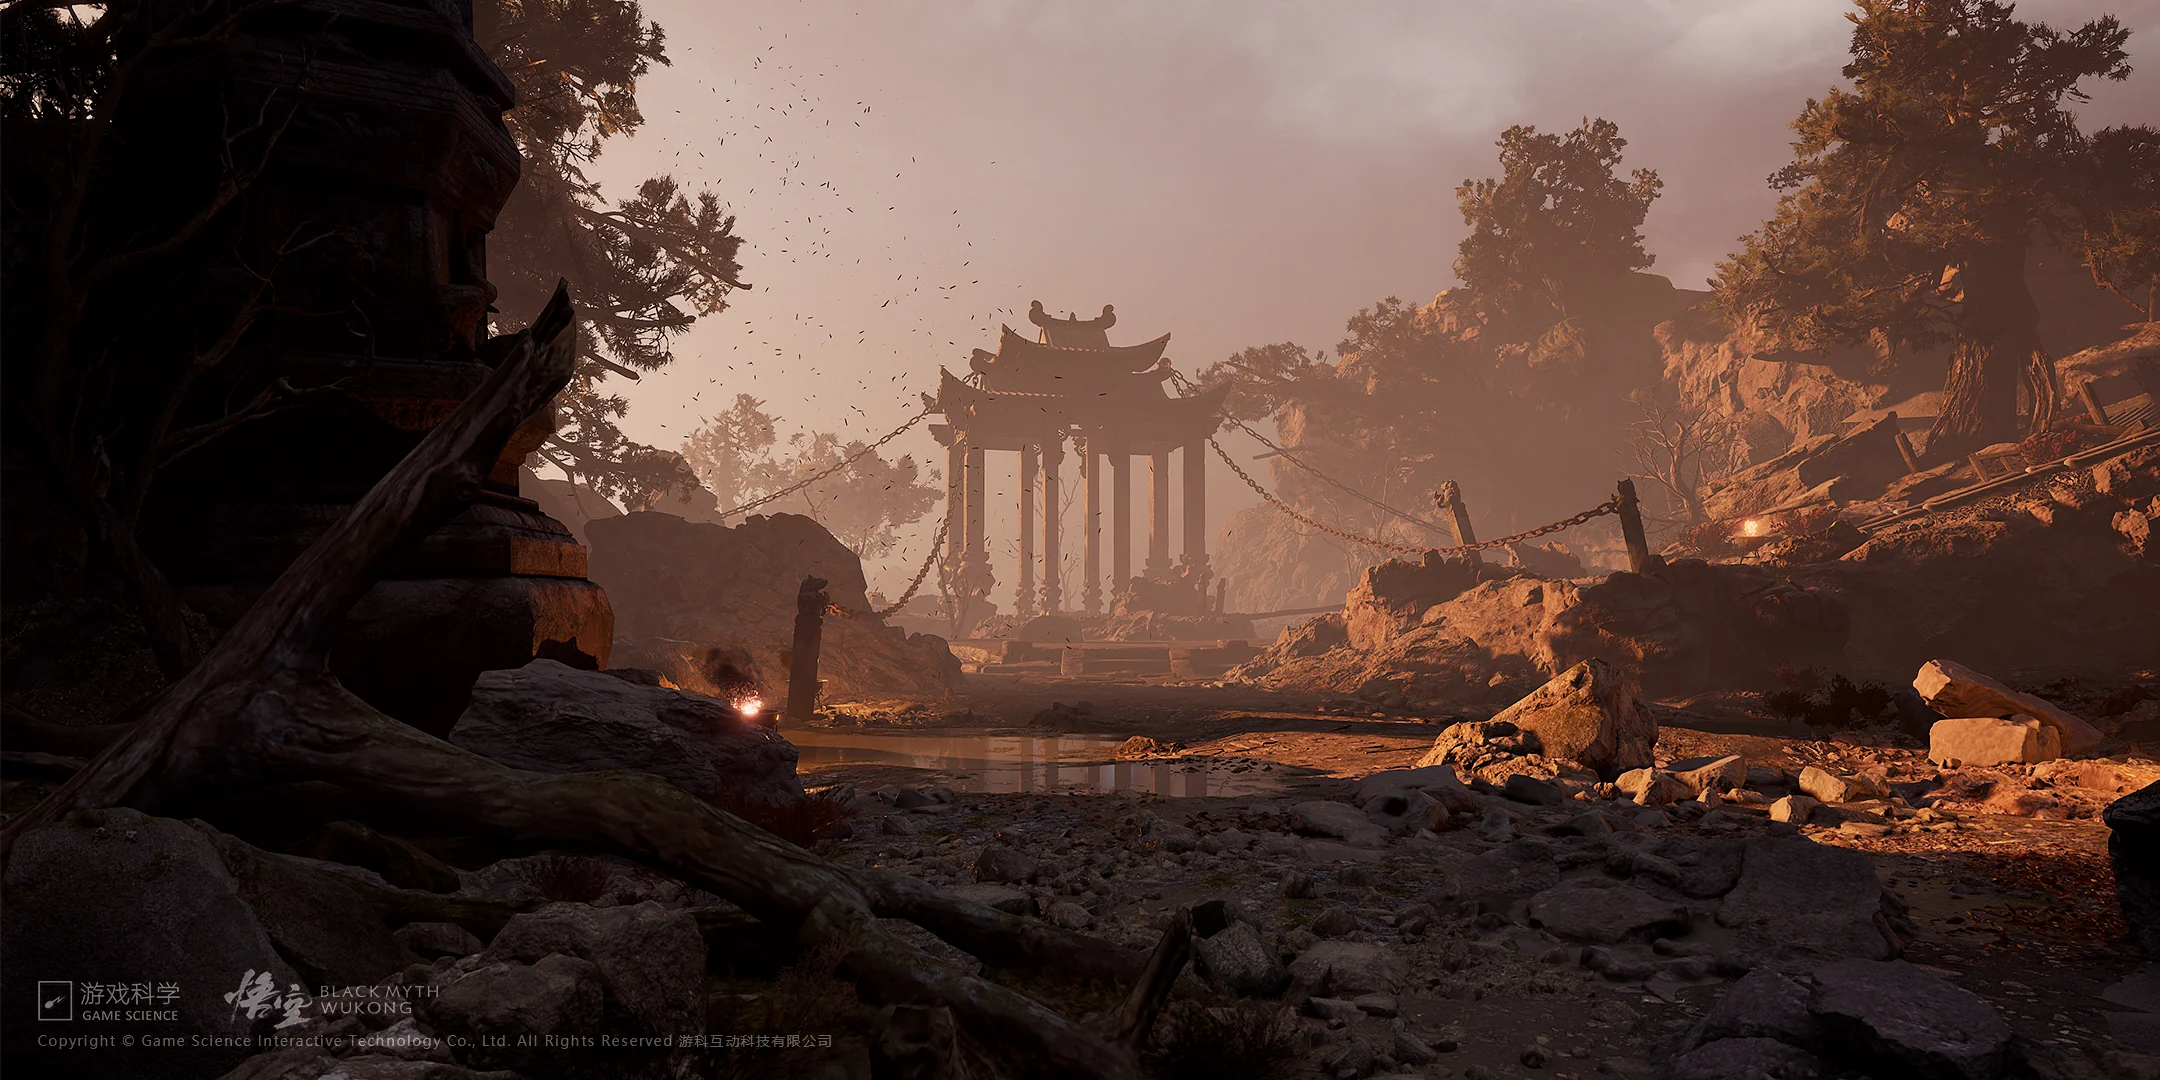
They said only Nixon could go to China, but these days China comes to you. In 2024, Game Science's Black Myth: Wukong became the second most played game in Steam's history: a big budget action game inspired by Journey to the West, a novel every Chinese schoolchild knows. Genshin Impact and Honor of Kings had already gone global, and Chinese developed games earned 20.5 billion dollars overseas in 2025. At home sit 683 million players spending 350.8 billion yuan in 2025, twice as many players as the United States has people. The traffic runs both ways: League of Legends and Clash of Clans belong to Tencent, a position the US government is reported to be reviewing. Unsurprisingly, China manages protects its game industry. Nothing releases in the market without a publication licence, the 版号 (banhao). Play time for under 18s is officially restricted to an hour a day, on Fridays, weekends and holidays.
Market sizeActual sales revenue · 2025
¥350.8B
- Mobile 257.1
- PC 78.2
- Console 8.4
- Other 7.2
Game usersUser base · 2025
683M
A record high. The report does not say what counts as a user, over what period, or at what age.
Rough scale only. Every market counts players differently, and MENA and IN have no figure.
Photograph GamesSci
Shape
Who plays and where the money goes, from the industry committee's annual report.
- 683Mgame users, a record high
- 73%of domestic revenue from mobile
- +86%console growth in 2025, a third straight year
- ¥291.1Bearned at home by Chinese-made games
- $20.5Bearned overseas, counted separately
Play is mobile dominated with a fast shifting periphery. Mobile takes 257.076 billion yuan of the 2025 domestic total, roughly 73 percent, client PC games take 78.16 billion yuan, console games take 8.362 billion yuan growing 86.33 percent in a third straight year of rapid growth, and web games decline for a tenth consecutive year.
China primarily makes what it plays and exports at scale. Self developed games earn 291.095 billion yuan domestically in 2025, up 11.64 percent, and 20.455 billion dollars overseas, up 10.23 percent, a sixth consecutive year above 100 billion yuan, with the United States, Japan and Korea taking over half of overseas revenue.
CGIGC annual report via 蓝鲸新闻 on 东方财富, financial news service
The internet base behind the market is 1.123 billion netizens at 79.7 percent penetration as of June 2025, per the CNNIC 56th statistical report.
Research note
Do not add overseas revenue to the domestic market. The 20.455 billion dollars self-developed games earn overseas is reported separately from the 350.789 billion yuan domestic figure; a chart that folds a Chinese publisher's overseas earnings into the Chinese market is measuring Chinese companies, not Chinese players.
Research note
Mini-program games are their own line. The report gives 53.535 billion yuan for mini-program games beside 257.076 billion yuan for mobile games, and the summary does not say whether one sits inside the other, so do not add the two and do not read the mini-game growth as extra to mobile.
Where players talk
Most international platforms are blocked, so games talk runs through domestic apps, all of them operating under censorship requirements.
Blocked
Most international platforms are blocked
- Google (struck through)
- YouTube (struck through)
- Facebook (struck through)
- X (struck through)
- Instagram (struck through)
- Reddit (struck through)
- Wikipedia (struck through)
- WhatsApp (struck through)
- Telegram (struck through)
Google search since 2012, Reddit since 2018 and every language of Wikipedia since 2019. Do not reach for them when researching Chinese games discourse.
Domestic
WeChat and Weibo fill the space
- WeChat 微信
- Weibo 微博
Freedom House ties the growth of WeChat and Sina Weibo directly to the blocks on international platforms, and both operate under government censorship demands.
Research note
Disclose bilibili's dual role wherever you cite it as a venue. bilibili operates as a major video community and simultaneously holds game publication approvals as a licensed publisher, with both imported and domestic titles on 2025 approval lists.
证券时报 coverage of August 2025 approval lists, securities daily
Unverified
Do not assert the Chinese streaming and forum layer without verification. Huya, Douyu and Douyin live, and the forums NGA, TapTap and Baidu Tieba, are widely described as core games venues, but their current scale and games activity could not be verified to standard from outside the country.
Where the data lives
The seven places to open first. The full list of 34 is at the bottom of the page.
NPPA game approval lists
Monthly public lists that confirm whether a game is licensed for China, when it was approved and which domestic publisher holds the approval.
中国游戏产业报告 (China Game Industry Report)
Domestic revenue, user scale, platform splits, self-developed and overseas revenue, released each December. The headline summary is free through state media and trade press.
CNNIC 统计报告 (Internet Development Statistical Report)
Twice yearly: netizen scale, penetration and user counts for major application categories, including online games.
Tencent investor relations
The market's largest publisher: games revenue split domestic and international, deferred revenue and title commentary, in English and Chinese.
中国政府网 policy library
The central government's policy database, hosting the full regulatory texts on games, including the minors play-time notice.
Freedom House, Freedom on the Net
Which international platforms are blocked and how content control works. The standard free reference when planning China research.
The State of Video Gaming (Ball, Epyllion)
Cross-market sizing, participation and platform charts that no single free source provides. It assembles many vendors, so cite the underlying source where the deck names one.
People
People worth following for this market, most of them analysts and reporters writing about it in English.
Communities
The forums and streaming sites usually named for China could not be verified from outside the country.
Heybox (小黑盒, Xiǎohēihé)
Where mainland Chinese PC and console players follow game news, post, wishlist and buy Steam keys, in a companion app whose database mirrors nearly all of Steam whether or not a game is licensed in China. A released game's page, keyed by its Steam app ID, carries a Heybox score from verified owners only; the key-sales and most-wishlisted charts appear only in the app. Heybox player counts include linked users' public Steam friend lists, so they measure reach, not ownership. User figures are the operator's own, from 22 million users and 800,000 a day in 2020 to 80 million cumulative across all its apps, and no independent audience figure could be found.
StakeThe operator earns a margin on Steam keys, sells ads and publishes games itself, so it has a commercial stake in games its community rates.
Gap
TapTap is held as a data row rather than a community. Treat any board or streaming figure as that platform's own claim.
34 curated sources for China
Research it yourself
These rows
10 of 10 sources
| Name | What it lets you find out | Type | Cost | Markets |
|---|---|---|---|---|
| Niko Partners (Niko IQ) | The specialist source for China, SEA, and MENA games markets, with informative free summaries. Paid reports are expensive and the free layer is summary-level. Also tracks Chinese publishing licence approvals and explains regulation for outside readers, which pairs with the NPPA primary source. Enterprise pricing is custom. Free blog summaries. | Market research firm | Paid | |
| Newrank (新榜, Xīnbǎng) | Longest-standing CN new-media data platform offering the proprietary NRI index across WeChat, Douyin, Xiaohongshu, Kuaishou, Bilibili and Weibo, with daily/weekly/monthly rankings including MCN influence charts. +86 phone registration typically required. Not accessible in full from outside CN without workarounds | Creator tracking | Freemium | |
| Feigua (飞瓜数据, Fēiguā Shùjù) | Douyin/Kuaishou/Bilibili streamer and live-commerce rankings (the standard tool for who is big on Douyin gaming). Commerce-metric weighted, +86 registration, access constraints from outside CN Limited free content. | Creator tracking | Paid | |
| Chanmama (蝉妈妈, Chánmāmā) | Douyin + Xiaohongshu creator/live rankings, a good complement to Feigua. Similar access restrictions as other Chinese sources Limited free content. | Creator tracking | Paid | |
| TopKlout (克劳锐, Kèláoruì) | Downloadable reports without login, including creator value rankings and collaboration charts. Annual MCN industry reports are the standard reference on CN's MCN ecosystem. Report cadence uneven, no site search | Creator tracking | Free | |
| DoHuya | Viewership metrics for DouYu and Huya from the Streams Charts family (a rare English-language window into CN game live streaming). Two platforms only. Misses Douyin/Bilibili live, which now dominate | Creator tracking | Freemium | |
| Gamma Data | The GPC report's official data partner. Monthly/quarterly market reports, segment studies (女性向, mini-games, AI). Distribution is WeChat-public-account-first, the single biggest access friction for outside researchers: the full reports go to readers who follow its account 游戏产业报告 and add its enterprise WeChat. Its own site is gone, so the link is its column on Gelonghui, which mirrors the posts with their headline figures. | Market research firm | Free | |
| TapTap (CN) | China's leading game discovery store and community, and the most legible public surface for CN genre and tag vocabulary, the source for the CN terms on the Genres tab. Category and tag labels appear on award pages, collections and game pages. The CN edition is taptap.cn and the global edition taptap.io. A swarm of lookalike mirror domains exists, use the two official domains only. Reviews and ratings are community sentiment, not evidence of fact. | Genre taxonomy | Free | |
| Tencent IR | The single best free window into Chinese gaming and its global ownership web (Riot, Supercell, stakes everywhere) | Corporate IR | Free | |
| NetEase IR | Second biggest CN major with notable JP studio investments | Corporate IR | Free |